PayID pokies in Australia: what the payment means
 Available in AU
PayID can move funds through Australia’s New Payments Platform, but its availability does not establish that an online casino may serve Australians.
Table of Contents
PayID’s Place in Australia’s Online Pokies Landscape
PayID belongs to Australia’s payment infrastructure, not to the lawfulness of whatever a payment might buy. It lets a person send money using an identifier such as a mobile number or email address instead of entering conventional bank details. The service operates through the New Payments Platform (NPP), which enables transfers between banks to move quickly. That describes a way money can travel. It says nothing, by itself, about whether a business may lawfully provide a particular service.
That distinction matters in discussions of PayID pokies online. A payment method can be familiar and functional while the activity attached to it remains prohibited. Under the Interactive Gambling Act 2001, operators are prohibited from providing real-money online casino games—including pokies—to people physically located in Australia. The legal question concerns the service and its provision, not whether the payment screen displays a recognisable Australian system.
A payment rail is not a permission slip.
PayID’s presence on a website, or a claim that it can be used there, cannot establish that the site is licensed to offer real-money casino games in Australia. Nor does it demonstrate fairness, transparent game information, or a willingness to pay winnings. These are separate claims, and none follows from the name of a payment method. A familiar identifier may make a transaction look ordinary; it does not make the underlying arrangement lawful.
When considering PayID pokies in Australia in 2026, check which operator details are actually available before choosing where to play. This overview highlights the stated licensing and payment information without assuming unlisted PayID terms.
1. Rollero Casino
License: Curacao Gaming Control Board OGL/2023/176/0095 (Hollycorn N.V.) Rollero Casino lists a Curacao Gaming Control Board licence, OGL/2023/176/0095, held by Hollycorn N.V.
2. 7Bit Casino
License: Curacao, operated by Dama N.V. 7Bit Casino is operated by Dama N.V. and is listed as licensed in Curacao.
3. JustCasino
License: Curacao Gaming Control Board JustCasino is listed with a Curacao Gaming Control Board licence.
4. Bizzo Casino
License: Curacao Gaming Control Board (TechSolutions Group N.V.) Bizzo Casino is listed with a Curacao Gaming Control Board licence, with TechSolutions Group N.V. named.
5. SkyCrown
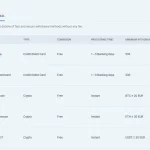
License: Tobique Gaming Commission · Payout speed: crypto ~10-15 minutes, fiat 1-5 days · Min. deposit: A$30 SkyCrown lists a Tobique Gaming Commission licence and a minimum deposit of A$30. Its stated payout times are around 10–15 minutes for crypto and 1–5 days for fiat.
6. Uptown Pokies
License: Curacao (operating since 2017) · Min. deposit: A$20 Uptown Pokies is listed as operating since 2017, with a Curacao licence and a minimum deposit of A$20.
7. DragonSlots Casino
License: Curacao Gaming Authority (Jumpman Gaming Ltd) DragonSlots Casino is listed with a Curacao Gaming Authority licence, with Jumpman Gaming Ltd named.
8. Kingmaker
Payout speed: crypto ~90 minutes, fiat 1-5 days · Min. deposit: A$30 Kingmaker lists a minimum deposit of A$30. Its stated payout times are around 90 minutes for crypto and 1–5 days for fiat.
9. House of Pokies
License: international iGaming licence – jurisdiction not named in the source · Payout speed: PayID 1-24 hours · Min. deposit: A$30 (PayID from A$10) House of Pokies lists an international iGaming licence, though the jurisdiction is not named. Its stated PayID payout time is 1–24 hours, with PayID deposits from A$10 and a general minimum deposit of A$30.
10. Wild Tokyo
License: Curacao · Payout speed: crypto 30-60 minutes, fiat 1-5 days · Min. deposit: A$10 Wild Tokyo lists a Curacao licence and a minimum deposit of A$10. Its stated payout times are 30–60 minutes for crypto and 1–5 days for fiat.
There is a small historical irony in this. Payment systems are designed to make the movement of money more efficient across everyday commerce. Their usefulness comes from being infrastructure rather than a verdict on every transaction they carry. A fast transfer system does not examine the social meaning of each payment before it moves. That work belongs elsewhere: to the rules governing the service, and to the institutions responsible for applying them.
For Australians, the legal setting is not a matter of whether an offshore casino has placed a PayID logo beside other payment symbols. The law treats online casino-style games, including slots, as prohibited interactive gambling services when supplied to customers in Australia. The Australian Communications and Media Authority is the regulator associated with enforcement of the interactive gambling framework. A foreign business may describe its own credentials in terms that sound reassuring, but those descriptions do not alter the Australian restriction on supplying the service to people here.
This is why a search for new PayID pokies online can produce a misleadingly tidy picture. Payment pages often present methods as a menu: select one, follow the instructions, move on. The menu is not a map of what is permitted. It records what a site claims it can process, not what Australian law allows it to offer. The difference is easy to miss precisely because payment interfaces are designed to make financial steps feel routine.
Bitcoin pokies in Australia: payments and rules
There is also a practical distinction between PayID existing as a payment system and PayID being available in a particular cashier. A casino cashier is the venue’s own list of payment options. The general operation of PayID through the NPP does not mean every website accepts it, and a site’s claim of acceptance does not make the system universally available there. Availability must be represented by that site’s own payment information. That is a statement about its interface, not an endorsement of its service.
The distinction runs both ways. A payment option may be absent from a cashier even though PayID is an established Australian transfer method. Or a cashier may display the method while the broader service remains prohibited for Australian customers. Neither condition changes the other. The national payment system and a private website’s cashier occupy different layers of the transaction; legality sits outside both.
This can be an awkward arrangement for a society accustomed to treating digital convenience as a sign of modernity. The payment technology says that a transfer can be made quickly between banks. The gambling law says that operators must not provide real-money online casino games to people in Australia. There is no contradiction in those statements. One concerns the movement of funds in general; the other sets a boundary around a particular service.
Legal Warning
Under the Interactive Gambling Act 2001, operators are prohibited from providing real-money online casino games, including pokies, to people physically located in Australia.
Accordingly, PayID should not be read as a badge of approval, safety or suitability. Its role is narrower: it is an Australian digital payment system based on an identifier, operating through the NPP. Whether a given cashier lists it is a separate matter. Whether the site may lawfully provide real-money pokies in Australia is separate again—and the payment method cannot answer that question.
What PayID Changes—and What It Does Not
PayID changes the address used to direct a bank transfer. Instead of entering conventional account details, a sender can use an identifier linked to an account, such as a mobile number or email address. The transfer still moves through the banking system; the identifier is a simpler route to the destination, not a new kind of money.
That distinction matters in discussions of PayID pokies. The method can make a payment destination easier to identify, but it does not change what the payment is for, establish that a business is entitled to accept it, or make a transaction safer in every other sense. A familiar-looking identifier is still only an identifier. It says nothing by itself about the conduct of the party receiving funds.
There is a small piece of social history in this convenience. Bank transfers once required people to handle strings of account information, details that were easy to mistype and awkward to pass along. PayID makes the destination more memorable by tying it to a detail many people already know. The banking machinery remains behind the curtain. The address becomes more human; the transfer does not become less consequential.
Pay by Phone Casinos in Australia: Payment Guide
PayID operates through Australia’s New Payments Platform, which supports quick transfers between participating banks. In ordinary use, that means the identifier can help a payment reach the intended account without the sender having to work from a conventional account number and branch code. The benefit is practical rather than magical: fewer unfamiliar details to manage, while the underlying bank transfer remains a bank transfer.
That practical distinction is sometimes blurred in the language around new PayID pokies. A payment method may be convenient, but convenience is not evidence of a venue’s legitimacy, fairness or willingness to return funds. Nor does a payment option settle whether a service may lawfully be offered in Australia. Under the Interactive Gambling Act 2001, operators are prohibited from providing real-money online casino games, including pokies, to people physically located in Australia. Payment access does not alter that rule.
The cost question is more straightforward. PayID itself does not impose a transfer fee. Reputable venues also do not add a separate charge simply because a deposit or withdrawal uses PayID. That does not mean every cost associated with a transaction disappears: a bank or a service provider may have its own terms, and a venue’s broader payment conditions are a separate matter. The useful point is narrower. PayID’s own transfer mechanism is not charging a fee.
This is one reason the method can sound more attractive than older payment arrangements. A sender may see an identifier rather than a cluster of bank details, and there is no PayID transfer charge to deduct from the amount sent. But a fee-free route is not a guarantee that the recipient is trustworthy or that funds can be recovered if something goes wrong. Friction has been reduced; responsibility has not.
Attention: Once a PayID transaction is confirmed, it cannot be reversed through PayID.
The limitation is decisive: once a PayID transaction is confirmed, it cannot be reversed through PayID. A mistaken or unwanted transfer is not like an unsent message. The system’s speed and simplicity do not create a pause button after confirmation. That makes accuracy and deliberation part of the payment’s value, not an inconvenience that can safely be ignored.
This irreversibility is not unique to a particular use of PayID, and it should not be treated as a special warning attached only to gambling-related payments. It follows from the nature of a confirmed transfer. A recognisable identifier can reduce the effort involved in directing money, but it cannot undo a decision once the funds have been sent. The easier the address becomes to remember, the less visible the point of no return may feel. It remains there.
The phrase “new pokies PayID” can therefore suggest a novelty that belongs to the casino, when the change is really in the payment address. PayID is an Australian payment system, not a casino product and not a mark of approval. A venue’s use of it does not certify its status. In Australia, that distinction sits against a legal setting in which real-money online casino services are prohibited for operators serving people in the country. The payment rail and the service using it are separate questions.
For a general bank transfer, PayID’s appeal is plain: an easier-to-handle identifier and no fee charged by PayID itself. Its limits are just as plain: the transfer remains consequential, and confirmation makes it final. Ease of use should not be mistaken for protection. A shorter address is still a route for money to leave an account.
Aristocrat Online Pokies in Australia: What It Means
PayID in Australia: Bank Rules Still Apply
PayID runs through Australia’s New Payments Platform, where transfers between participating banks can move quickly. That speed does not make the payment method independent of the bank holding the account. A transfer still passes through the bank’s systems and remains subject to the limits and policies attached to that account.
A specialist payment review reports that the player’s bank sets the daily PayID transfer limit. The practical consequence is straightforward: the amount available to send is not determined by the casino’s payment page alone. A payment form may accept a requested figure while the bank applies a lower ceiling, or the bank’s own settings may prevent the transfer from being made at all. The relevant limit belongs to the banking relationship, not to PayID as a universal service.
That distinction matters because PayID can look like a single national instrument. An email address or mobile number stands in for conventional bank details, and the New Payments Platform makes the underlying transfer feel immediate. But the identifier is only the address on the envelope. The bank still decides what can leave the account and under what conditions.
The daily ceiling may also differ from the amount a payment recipient is willing to accept. These are separate controls, set by different parties. A casino’s listed minimum or maximum, where such information appears, cannot establish what an individual bank will permit. Nor does a failed transfer necessarily mean that the PayID identifier is wrong: a bank restriction or limit can produce a similar practical outcome. The error message, if one appears, is more useful than assumptions about the payment method.
Some Australian banks, including members of the Big Four, may block PayID transfers to known gambling merchants based on their acceptable use policies.
There is another point of friction. A specialist review reports that some Australian banks, including members of the Big Four, have at times blocked PayID transfers to gambling merchants they identify as known recipients, citing acceptable use policies. This is a reported possibility, not a fixed rule that applies uniformly across those banks or to every customer. Policies and enforcement can change, and a bank’s response may depend on the transfer and the merchant it recognises.
The phrase “known gambling merchant” is important. A bank’s decision may concern the recipient it has identified, rather than PayID itself. The method can remain available for ordinary transfers while a particular payment is declined. Conversely, the existence of PayID in a payment menu does not establish that a bank will approve a transfer to that recipient. Payment availability at one end and bank acceptance at the other are separate questions.
Banks are not neutral pipes in this arrangement. Their acceptable use policies express institutional decisions about which transactions they will process. That can make payment access feel inconsistent: the same system that carries an ordinary transfer quickly may not carry another transfer to a recipient the bank treats differently. Convenience is conditional.
A declined payment should therefore not be treated as an invitation to keep trying variations of the same transfer. PayID transactions become irreversible once confirmed, so a successful transfer is not equivalent to a card authorisation that can simply be withdrawn. If a bank refuses a payment, its own explanation and support channels are the appropriate place to clarify the restriction. Repeated attempts do not change the policy governing the account.
Dragon Link Online Pokies in Australia: Bitcoin Basics
There is also a broader Australian context that payment design cannot erase. The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games, including pokies, to people located in Australia. The presence of a PayID option on a site does not alter that legal position, and a bank’s willingness to process a payment would not certify the service. Payment rails answer a narrow question: whether funds can move through them. They do not supply approval for the activity at the other end.
For anyone assessing a payment page, the useful distinction is between what the operator displays and what the bank actually permits. The page may list PayID; the bank may set the applicable daily ceiling, decline a recognised gambling recipient, or allow the transfer. These outcomes are not interchangeable, and none can be inferred merely from the speed associated with the New Payments Platform.
The bank remains in the room.
Deposits, Withdrawals and the Names on the Account
A payment has two journeys: the one recorded by the bank and the one recorded by the casino. With PayID, the bank-side transfer can be quick; the casino-side handling is a separate process. That distinction matters because a payment appearing to leave one account does not, by itself, show that a casino has credited it, approved a withdrawal or released funds.
Do
- Match the casino account name with the bank-registered PayID name
- Ensure PayID details correspond to the identifier registered with the bank
Don’t
- Use a different account holder’s payment identifier
- Use a shortened name that creates a mismatch with bank records
There is also a legal boundary that cannot be tidied away by a cashier page. Under Australia’s Interactive Gambling Act 2001, providing real-money online casino games, including pokies, to people in Australia is illegal for operators. A PayID payment option does not make that service lawful, nor does the ability to send money establish that an operator is suitable or will return it. Payment access and the legal status of the service are different questions.
The deposit: bank to casino account
PayID uses an identifier registered with a bank, such as a mobile number or email address, rather than requiring the sender to enter conventional bank account details for every transfer. For a deposit, the casino’s instructions may direct a payment to an identifier or provide payment details through its cashier. The exact route depends on the arrangement presented by the service; the transfer itself remains a bank transaction.
PayID deposits at online casinos are described as completing within seconds. That refers to the transfer speed, not necessarily the time required for the casino’s account balance to update. A delay between those events can leave a payment looking complete in the banking app while the casino account has not yet reflected it. The distinction is mundane, but money has a habit of making mundane distinctions feel rather larger.
The name attached to the casino account should match the name associated with the bank-registered PayID. The same applies to the PayID details: they need to correspond to the identifier registered with the player’s bank. A mismatch can interrupt transaction handling and may create questions about who owns the funds. It is not a cosmetic discrepancy. A shortened name, a different account holder or use of another person’s payment identifier can complicate the link between the person named in the casino account and the person whose bank sent the money.
This matching requirement also shapes what happens later. A deposit made from one person’s bank details and a withdrawal requested by someone with a different casino profile do not form a clean, continuous record. Transaction checks are easier to understand when the account identity and payment identity belong to the same person. Where they do not, a payment may be delayed or disputed; no payment method can make the underlying identity question disappear.
The withdrawal: casino account to bank
PayID can also be used to send funds back, but a withdrawal is not simply a deposit played in reverse. The casino first has to process the request within its own system. Only after the operator releases the payment does the bank-side transfer begin. The speed of PayID therefore describes one leg of the journey, not every stage between request and receipt.
A specialist review has described casino-initiated PayID withdrawals as potentially sitting in a pending period of 24–72 hours before the funds leave the casino’s system. The same kind of review has described transfers taking 12–24 hours after approval, with the internal wait contributing to a total of 2–4 days from request to receipt. These are reported timings, not a dependable timetable for every venue or transaction. The important distinction is between a request still being handled by the casino and a payment already sent through the banking system.
Reported Withdrawal Timings
A specialist review reports that casino-initiated PayID withdrawals may sit in a pending period of 24–72 hours before leaving the system, with transfers taking another 12–24 hours after approval, totaling 2–4 days from request to receipt.
That distinction helps explain why a withdrawal can remain pending even though PayID is associated with quick transfers. The bank cannot process a payment that the casino has not yet released. Conversely, once the casino has sent it, any remaining delay belongs to the transfer stage rather than the operator’s internal queue. A status label such as “pending” or “processed” is therefore useful only when it is clear which institution’s work it describes.
The name match matters again on the return journey. If the PayID details supplied for a withdrawal do not match the PayID registered with the bank, the payment may not be routed as expected. A casino profile that differs from the bank-registered identity can raise a further verification issue before release. Keeping the account details consistent supports a traceable path from deposit to withdrawal; it does not guarantee that a casino will approve a request or pay it promptly.
One payment method, several points of control
The movement of funds involves at least two distinct systems: the bank’s transfer network and the casino’s account and review process. PayID operates through Australia’s New Payments Platform, which facilitates quick transfers between banks. That network does not decide whether a casino account is credited, whether a withdrawal is approved or how long an operator keeps a request pending.
Nor does a fast deposit settle the question of a later payout. A casino may have to complete its own processing before sending funds, and a player’s identity details must align with the bank-registered PayID. The practical record is thus more than a transfer receipt: it includes the identity attached to the payment, the casino account receiving it and the status of any withdrawal request.
The neatness of the payment trail is no verdict on the service behind it. A bank transfer can be technically successful while the operator’s conduct remains a separate matter. That is the small print of a fast payment.
Assessing PayID Casinos Without a Promised Winners’ List
A payment logo is an unusually small thing on which to build a large conclusion. PayID in a cashier can confirm that a payment route is offered; it cannot establish that an operator is lawful in Australia, that its games are fair, or that a requested withdrawal will be honoured. Those are separate questions, and a tidy-looking deposit screen answers only the first.
There is a further point that comparison pages can obscure. Under the Interactive Gambling Act 2001, providing real-money online casino games—including pokies—to people physically located in Australia is illegal for operators. PayID’s presence does not change that position or turn an offshore service into a locally authorised one. Payment access is not a legal credential.
Nor does a promise of a “best” venue solve the problem. A ranked list may suggest certainty where the important conditions vary from one operator to another and may change over time. A more useful comparison begins with what can be checked: whether PayID is actually shown in the cashier, what the withdrawal rules say, how the venue describes its review process, and what documents it requires before paying. Specific terms matter more than a label.
Withdrawal Thresholds
Reported minimum withdrawals range from AUD 20–50, with some operators deducting A$5–A$10 for amounts below A$100 or A$200.
KYC Verification
Identity and account information must be checked; until verification is complete, requests may remain under review regardless of the payment method.
Processing Speed
While the PayID network moves money quickly once sent, the total time depends on the operator’s internal approval and review process.
The cashier is a practical first checkpoint, not a recommendation. Payment methods can differ by account or be changed by the operator, so an old mention elsewhere is not proof that PayID is available at the point of use. The cashier’s wording should be read alongside the payment terms: a method may be listed while withdrawals are subject to separate conditions. The distinction is plain, if not always prominent.
Withdrawals are not simply deposits in reverse. A casino may review a request internally before releasing funds, and the outcome can depend on the account’s verification status. Specialist casino reviews describe this internal check and report that, after approval, a PayID transfer may reach the account within the same day. These are reported practices, not a timetable that PayID itself guarantees. The payment network can move money quickly once a transfer is sent; it cannot decide when a casino approves it.
That makes KYC status part of any serious assessment. If identity or account information still needs checking, the request may remain under review rather than moving directly to payment. A fast transfer method cannot remove that stage. Published terms should explain what verification is required and when it may be requested; unclear wording leaves the player unable to distinguish a payment delay from an unresolved account review. The distinction matters.
Casino Withdrawals Without ID Verification in Australia
Withdrawal thresholds are another point to compare, though they should not be mistaken for a prediction of service quality. Specialist reviews place reported PayID minimum withdrawals in the AUD 20–50 range. Some reviews also describe operators deducting A$5–A$10 from withdrawals below internal thresholds, often set at A$100 or A$200. These conditions are operator-specific and should be confirmed in the current cashier or terms, rather than treated as standard across the market. A low minimum does not demonstrate that a payout will be approved promptly.
The relevant comparison is therefore not a contest between payment badges. It is a reading of the whole withdrawal path: what must be verified, who reviews the request, what threshold applies, whether a deduction is stated, and what happens after approval. If the published terms answer none of these questions, the uncertainty is itself part of the assessment. A polished cashier cannot make it disappear.
PayID also says nothing about the operator’s willingness or ability to pay winnings. A venue may advertise a quick transfer while retaining control over the review that comes before it. That is why a quoted processing time should be read as conditional on approval, not as a promise from the payment system. The speed of the rail and the speed of the institution using it are different measures.
Best-Paying Online Pokies in Australia: What Claims Mean
For Australian readers, the legal setting remains decisive, not a footnote to a comparison. Online casino-style games offered for real money to people in Australia fall within prohibited interactive gambling services under the Act. A PayID option, a favourable review, or a smooth-looking withdrawal policy does not alter that status. The method can describe how money moves; it cannot make the underlying service permissible. No badge does that.
Real-Money Claims, Minimums and Bonus Conditions
“Real money” can make a payment claim sound more substantial than it is. A PayID label says something about the route a transfer may take; it does not establish that an online casino can lawfully provide real-money play in Australia, or that a balance shown on screen is readily withdrawable. The distinction matters because the Interactive Gambling Act 2001 prohibits operators from providing online casino games, including pokies, to people physically located in Australia. A payment method cannot alter that legal position.
Bonus and Deposit Conditions
- Minimum deposits typically range from AU$10–AU$20
- Bonus balances may require wagering multipliers of 30x–45x
- Exceeding maximum bet limits during wagering may void bonuses and winnings
- Some operators may apply withdrawal charges of AUD 2–5
The figures attached to offshore offers are best read as conditions, not invitations. A stated minimum deposit describes the smallest amount an operator says it will accept through a particular cashier option. It does not show what a player can ultimately recover, nor does it make the service suitable for Australians. Across operator terms, deposit entry points are often stated in the AU$10–AU$20 range. The precise threshold can still depend on the venue and payment option, so a headline amount should not be mistaken for a universal PayID rule.
A low entry amount is only one part of the cost. The terms may also set a minimum withdrawal, impose a charge, or make a bonus balance subject to wagering conditions. These details sit in separate corners of an offer, as if the money were simple at the point of deposit and complicated only when it is time to leave. That is a familiar imbalance in commercial language.
A specialist review has reported withdrawal charges of AUD 2–5 at some casinos. This is a reported condition, not a standard PayID fee and not a charge that applies across the market. PayID itself does not levy transfer fees, but an operator may set its own withdrawal terms. The distinction is plain but consequential: a no-fee payment network does not prevent a business from attaching a charge to a payout. The cashier and the written terms, rather than the payment method’s name, determine what an offer claims.
Bonuses add another layer. A bonus balance is not necessarily cash that can be withdrawn immediately. It may have to meet wagering requirements first, and a specialist review has reported requirements of 30x–45x the bonus amount. The applicable calculation and eligible play should be stated in the offer’s terms. Without those details, the headline bonus says little about the amount that could become withdrawable. A large-looking credit can carry a substantial obligation behind it.
Safe Online Pokies in Australia: Bitcoin and the Law
The maximum bet condition deserves particular attention during bonus wagering. If the terms set a maximum stake and that limit is exceeded while completing the requirement, the bonus and associated winnings may be voided. This is not a minor technicality: it can change whether a displayed balance remains eligible for withdrawal. Bonus conditions should therefore be read as a connected set—wagering, eligible games, maximum stake and expiry—rather than as a single promotional number.
There is also a difference between a cash balance and a bonus balance. Offers may separate deposited funds, bonus credit and winnings generated under bonus conditions, each with its own rules. The label shown beside a balance does not settle what may be withdrawn. What matters is the operator’s stated process for clearing the requirement and the consequences if a condition is breached. Multiple accounts at one casino can create further risk; operators may treat them as a breach and restrict accounts or forfeit winnings.
These terms should not be mistaken for consumer protections. Clear arithmetic can make an offer easier to understand, but it cannot establish that the underlying service is lawful in Australia or that a payout will be honoured. Nor does PayID availability certify fairness, transparency or an operator’s willingness to pay. The Australian Communications and Media Authority administers the framework under which the provision of real-money online casino games to people in Australia is prohibited. A polished cashier does not change that.
The useful distinction, then, is between a transaction claim and a promise about the whole experience. A stated deposit floor, a possible withdrawal charge and a wagering multiplier describe conditions attached to money. They do not turn an offshore real-money offer into a lawful Australian casino service. Small print, large consequences.
How do I deposit money into an online casino using PayID?
If a site’s cashier lists PayID, select it and use the PayID registered with your bank; deposits typically arrive within seconds. Your bank may block transfers to gambling merchants.
Does PayID charge fees for casino deposits or withdrawals?
PayID itself does not charge transfer fees, but some casinos charge A$2–A$5 per withdrawal or deduct A$5–A$10 from withdrawals below their thresholds. Check the casino’s payment terms for its charges.
How long do PayID cashouts usually take?
After casino approval, PayID transfers usually arrive the same day. A casino’s pending period and review can make the total time from request to receipt around 2–4 days.
Payments
Anonymous Crypto Casinos in Australia: Risks & Access
Bitcoin deposits can fluctuate in value, while offshore account checks and access restrictions remain separate...
Aristocrat Online Pokies in Australia: What It Means
The phrase does not identify a specific game or prove online availability; free play and...
Aussie Crypto Casinos: Rules, Payments and Claims
A practical look at operator claims, Australian rules, crypto transfers, and the limits of what...
New Australian online pokies: law, access and risks
The guide separates Australian law from offshore offers and explains what release labels, account checks,...
Online Casino Payment Methods for Australians
Deposits and withdrawals can follow different routes, with processing, fees, currency conversion and account checks...
Best-Paying Online Pokies in Australia: What Claims Mean
The guide explains how return figures, offshore rules, payment steps and bonus conditions shape claims...
Bitcoin pokies in Australia: payments and rules
Bitcoin is only the transfer method; the operator supplies the game and account, within a...
Amex Casino Sites in Australia: Acceptance and Limits
Amex availability varies by service, and a card option does not make an Australian-facing online...
Casino Sites and BPAY in Australia: What Is Known
It distinguishes everyday payment familiarity from casino-specific evidence, including separate questions about deposits and withdrawals....
Casino Sites That Accept Credit Cards in Australia
Card acceptance varies by operator, and Australian law restricts real-money online casino games for people...
EcoPayz Casino Sites in Australia: What Is Confirmed
The article distinguishes general references to EcoPayz from confirmed cashier options and explains why deposit...
Osko Casino Claims in Australia: What the Evidence Shows
Osko's everyday banking role does not establish that an offshore casino accepts it or that...
Paysafecard and Australian casino sites: what is verified
A payment method alone cannot show whether a casino accepts deposits, supports matching withdrawals or...
Skrill casino sites in Australia: what is known
Skrill references alone cannot establish whether a casino accepts deposits, pays withdrawals, or may lawfully...
Trustly Casino Sites in Australia: What’s Verified
Trustly’s presence in search wording does not establish that Australian operators offer it for deposits...
Under-an-Hour Casino Withdrawals in Australia
A withdrawal’s speed depends on both the casino’s checks and the payment route that carries...
Casino Withdrawals Without ID Verification in Australia
Registration may be low-friction, but casinos must verify identity before processing withdrawals; payment speed depends...
Casinos That Accept Apple Pay in Australia
Australia’s widespread use of mobile wallets does not confirm that a particular casino accepts Apple...
Bitcoin Casinos in Australia: Legal and Practical Guide
Bitcoin is a payment method, not a legal shortcut: Australian rules focus on the service...
Bitcoin Cash Casinos in Australia: Access and Licensing
BCH payment availability does not establish Australian authorisation, so payment checks and casino terms need...
Casinos That Accept CashToCode in Australia
The article puts CashToCode in context and explains why payment acceptance, withdrawals and game availability...
Ethereum Casinos in Australia: Legal and Payment Facts
Ethereum is only a payment method; the article separates payment claims from the legal status...
Casinos That Accept Google Pay in Australia
Australian payment habits do not establish which gambling operators accept Google Pay or what their...
Casinos That Accept Litecoin in Australia: What’s Known
A careful look at payment claims, game availability and the limits of evidence for Australian...
Casinos That Accept Mastercard in Australia: Rules
Australian rules govern the casino service itself, while card availability, verification and withdrawals remain separate...
Casinos That Accept MiFinity in Australia: Evidence
MiFinity support is operator-specific, while game availability and Australia’s restrictions are separate questions. Mifinity and...
Neosurf Casinos in Australia: What the Evidence Shows
The article distinguishes payment-site claims from verified details and explains the legal context for real-money...
Casinos That Accept Neteller in Australia: What to Check
A cautious guide to checking cashier claims, offshore status and withdrawal language without treating them...
Casinos That Accept PayID in Australia: What to Know
Australia’s widespread use of cards, mobile wallets and bank-linked services does not establish that a...
Casinos That Accept PayPal in Australia: What to Check
PayPal’s place in everyday payments does not confirm casino deposits, withdrawals, or promotions, so each...
Casinos That Accept POLi in Australia: What to Check
A cashier listing, a completed deposit and availability to Australian account holders are distinct claims....
Casinos That Accept Tether USDT in Australia: What’s Verified
A payment label alone does not establish that an operator accepts USDT or explain its...
Casinos That Accept Visa in Australia: What to Know
Visa availability varies by operator, and a payment option alone does not establish transaction approval...
Dragon Link Online Pokies in Australia: Bitcoin Basics
A practical distinction between physical cabinets and screen-based games, with notes on free play, casino...
Easy Withdrawal Casinos in Australia: How Payouts Work
Withdrawal speed depends on both the operator’s approval process and the payment route used to...
Fast Withdrawal Casinos in Australia: Payment Routes
Withdrawal timing depends on both the casino’s processing and the onward payment method, which may...
Instant Bank Transfer Casinos in Australia
The guide separates NPP payment settlement from casino account processing, then follows deposits, withdrawals, bonuses...
Instant PayID Withdrawals in Australia: How They Work
PayID can transfer released funds in real time, but the operator’s review and approval happen...
Instant PayID Withdrawals for Australian Casinos
PayID can move released funds in real time, but casino approval, bonus terms and account...
No-KYC Casino Australia: Payments and Verification
Payment speed does not establish what identity checks apply, and the rules around deposits and...
Online Pokies Instant Withdrawals in Australia
A withdrawal can be called instant after release even when checks, bonus conditions or payment...
Online Pokies PayID in Australia: Deposit Facts
PayID is a bank-to-bank payment rail, while deposit limits, account checks and withdrawal timing are...
Pay by Phone Casinos in Australia: Payment Guide
PayID can use a mobile number as an identifier, but the deposit is authorised through...
Quick casino withdrawals in Australia: how payouts work
Cashout timing depends on the payment method, casino processing and cleared bonus terms, while Australian...
Real Cash Online Pokies in Australia: What Counts?
Bitcoin deposits, in-game credits and withdrawable value are distinct, while account checks and payment steps...
Safe Online Pokies in Australia: Bitcoin and the Law
The guide explains the Australian legal context, payment steps, verification, and the limits of security...
Same-Day Payout Casinos in Australia: What It Means
A withdrawal can be approved before funds move, so payment method, checks and terms shape...
Solana Casino Comparison Australia: Law and Payments
SOL does not change the legal status of an offshore casino, while payment routes, bonus...